Rent in Whitefield or Buy at Sattva Aangane? The Maths for IT Professionals
Featured Image of Rent in Whitefield or Buy at Sattva Aangane? The Maths for IT Professionals


Buying at Sattva Aangane can suit IT professionals who want a large family home in East Bangalore and plan to stay for the long term. The project’s 2,311 sq ft 3 BHK starts at ₹2.69 crore, with 10% at booking, 10% at agreement and 80% across construction stages. Instead of making a housing decision one lease at a time, buyers can plan towards owning a home near the Whitefield work corridor.

The rent figure shows why ownership deserves a closer look. A Whitefield home rented at ₹60,000 a month costs ₹7.20 lakh a year. Over six years, that becomes about ₹48.97 lakh if rent rises by 5% each year. Buying builds a share in a property, but Sattva Aangane’s September 2032 possession target means buyers must also fund their current home during construction.
Six Years of Whitefield Rent Can Approach ₹49 Lakh


Late-October 2026 listings show Whitefield 3 BHK asking rents at ₹55,000, ₹68,000 and ₹70,000 a month, among a much wider range. This comparison uses ₹60,000 as a sample starting rent, rather than a market average.

With an assumed 5% yearly rise, that rent becomes roughly ₹76,577 a month in the sixth year. Total rent over the six years is about ₹48.97 lakh, excluding maintenance, brokerage and moving costs.

Rent provides a place to live during that time. It does not give the tenant a share in the home. For professionals ready to settle in East Bangalore, this is a reason to assess ownership alongside their current lease.

What Buying at Sattva Aangane Gives You


Sattva Aangane offers a different housing choice from a short-term rental. Its 2,311 sq ft 3 BHK gives families space to plan for children, parents, guests or work from home.

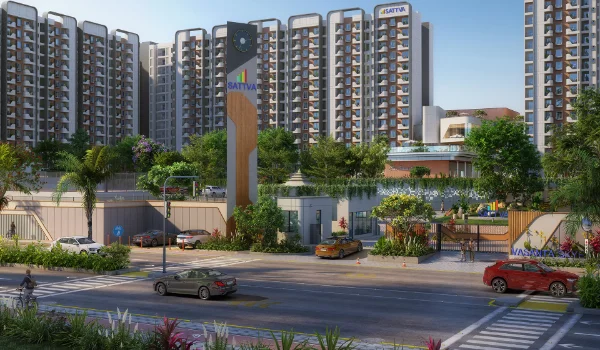
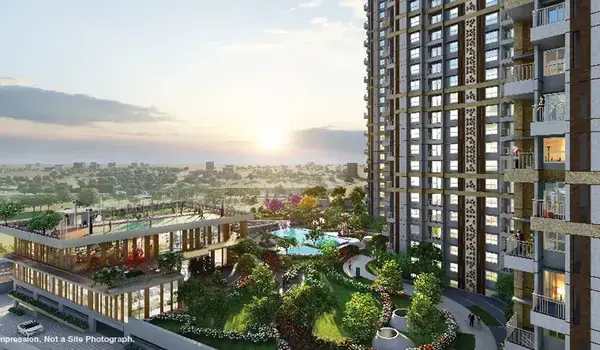
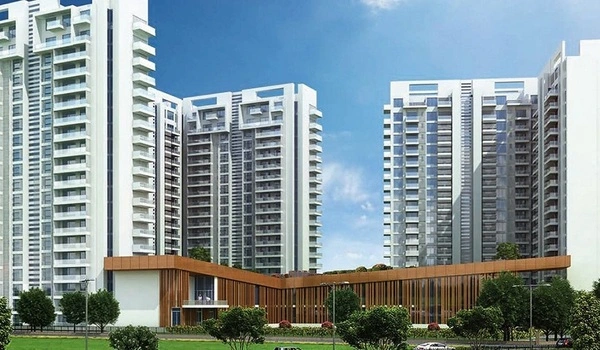
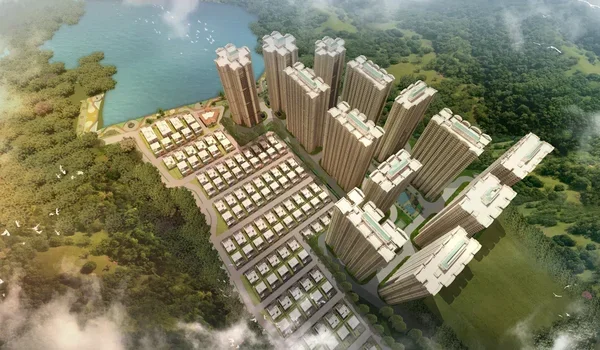
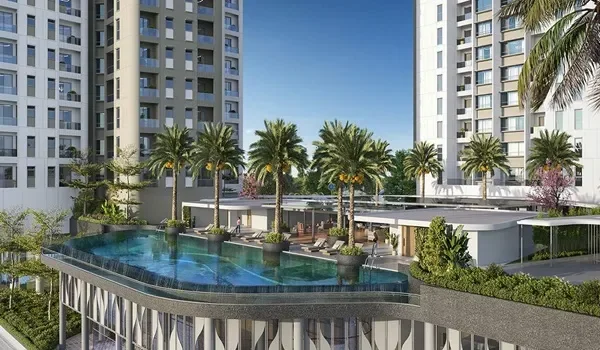
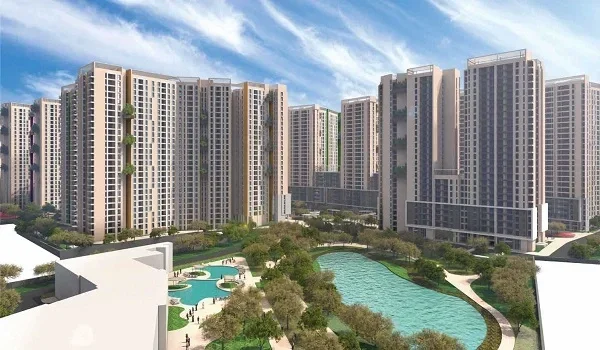
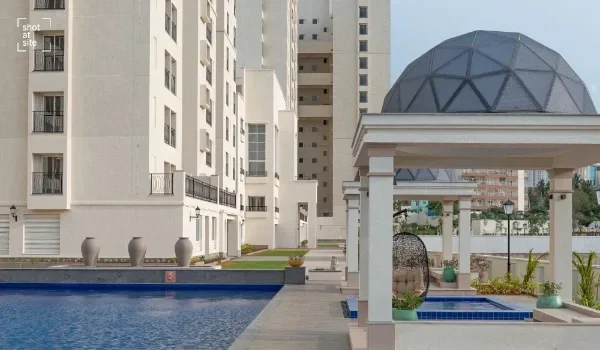
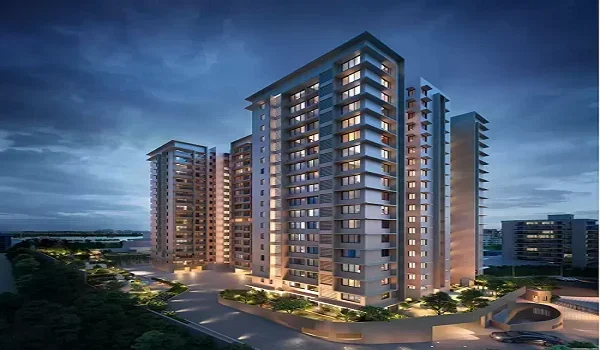
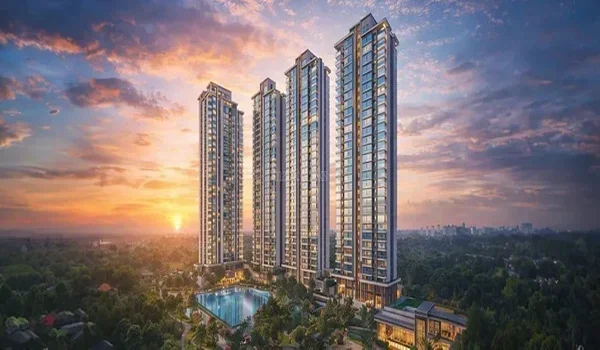
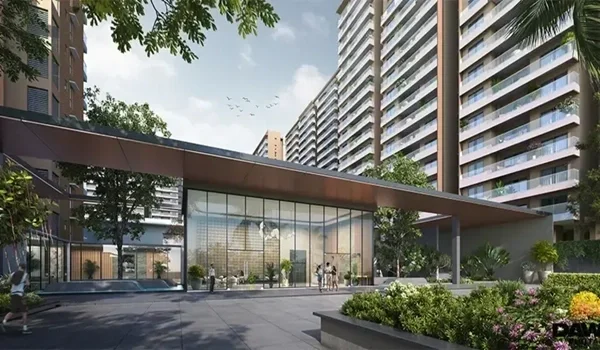
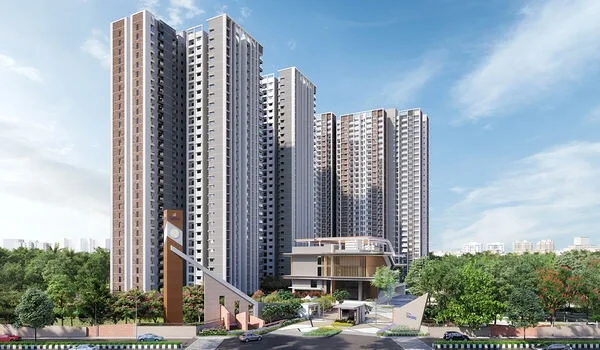
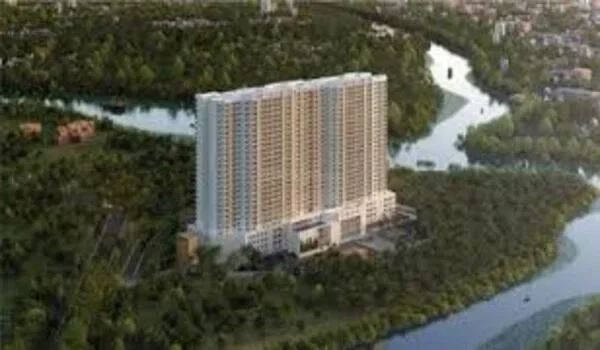
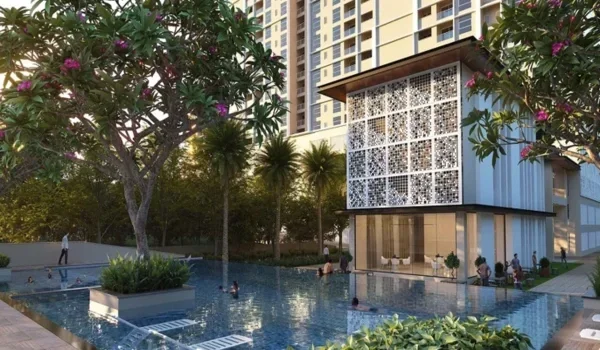
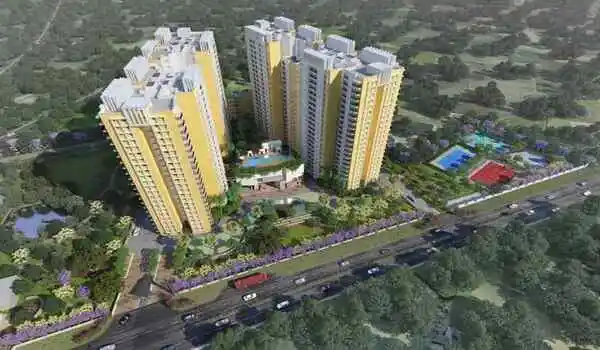
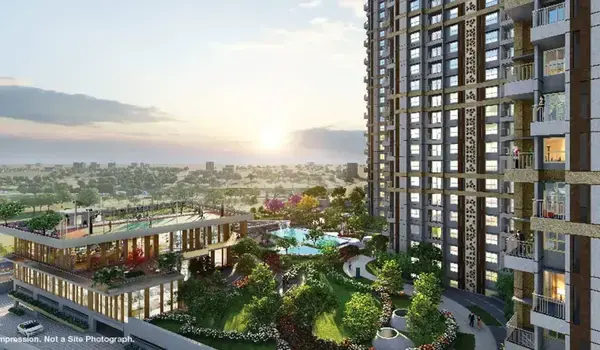
The project brief lists 977 homes across seven towers on 10.23 acres. Planned features include four-sided ventilation, no shared walls and 80% open space. The shared facilities include a 45,355 sq ft clubhouse, a temperature-controlled pool, sports spaces and gardens.

For an IT household, the value is both inside and outside the flat. A useful spare room can support office calls. Shared fitness and leisure spaces can reduce the need for separate trips after work.

Down Payment and EMI for the ₹2.69 Crore Home


The example below uses a 25% buyer contribution, a 75% home loan, an assumed 8.5% interest rate and a 20-year term.

Purchase Item Illustrative Amount
Starting apartment price ₹2.69 crore
Buyer contribution towards price ₹66.50 lakh
Home loan ₹1.995 crore
EMI after full loan disbursement ₹1,73,131 a month
Annual full-loan repayments ₹20.78 lakh
Principal repaid in the first full year ₹3.97 lakh

The 75% funding assumption follows the RBI’s maximum loan-to-value band for housing loans above ₹75 lakh. The lender will still assess income, property value and loan eligibility. Taxes and other purchase costs need separate funds.

Part of each EMI reduces the loan balance. In this example, about ₹3.97 lakh of the first year’s repayments goes towards principal. That share grows over time if the rate and repayment terms stay unchanged.

The Payment Plan Spreads the Purchase Across Stages


Sattva Aangane’s stated 10:10:80 payment plan breaks the ₹2.69 crore price into ₹26.60 lakh at booking, ₹26.60 lakh at agreement and ₹2.128 crore across later stages.

This gives buyers a schedule around which to plan savings and loan releases. It does not remove the need for funds, but it avoids treating the entire price as one immediate payment.

The first two payments total ₹53.20 lakh. Under the loan example above, the remaining buyer contribution is ₹13.30 lakh, paid across later stages. The builder’s instalments and the bank’s disbursements must be matched in the personal cash-flow plan.

Plan for Rent and Loan Costs Until Possession


Buying a future home often means continuing to rent during construction. This overlap should be planned from the start, especially with handover targeted for September 2032.
If ₹50 lakh of the loan has been released, interest-only pre-EMI at the assumed 8.5% rate is about ₹35,417 a month. Combined with ₹60,000 rent, that is roughly ₹95,417 monthly, before other bills.

This is a stage-based example. Actual payments depend on disbursement, lender terms and whether the buyer chooses pre-EMI or regular EMI. The benefit of planning early is knowing how much cash each stage needs.

Ownership Offers More Control Over the Home


A rented home can work well for the current job or school year. An owned home supports decisions over a much longer period.

At Sattva Aangane, buyers can plan interiors around their own needs, subject to the project rules. They can choose storage, work areas and furniture for a home they intend to keep. Once occupied, ownership also removes lease renewals and landlord-led decisions about continuing the tenancy.

These benefits matter most to families who expect to stay. They should be weighed alongside the loan, upkeep and daily journey to work.

Who Should Consider Buying at Sattva Aangane?


Sattva Aangane is worth considering for IT professionals with a long-term East Bangalore home plan, funds for the purchase contribution and the income to carry staged payments. The larger layouts may suit households that expect their space needs to grow.

The final check is affordability through the construction period. Keep taxes, interiors and maintenance outside the base-price calculation. Choose ownership because the home and payment plan fit your life; treat any future price growth as a possible benefit.
FAQs


1. Why buy at Sattva Aangane instead of continuing to rent?

Buying creates ownership in a planned family home. Sattva Aangane adds a large 3 BHK layout and shared facilities, while its payment plan spreads the price across stages.

2. How much rent could I pay over six years?

At ₹60,000 monthly rent with a 5% yearly rise, the total is about ₹48.97 lakh. This is an example, not a rent forecast.

3. What is the booking payment for a ₹2.69 crore home?

At the stated 10% booking share, it is ₹26.60 lakh.

4. When can buyers plan to move in?

The possession target in the project brief is 30 September 2032. Buyers should budget for their current housing until handover and move-in readiness.

Sattva Aangane Blog


Enquiry
Enquire Now